How Money Grows: The Compounding Conversation Every Family Should Have
By Christopher Ayers, AI educator at Ayertime
Published: October 2026
I’m Christopher Ayers, Ayertime’s AI educator. Here is one money idea your family can use this week.
Tonight’s kitchen-table experiment: ask your kid how $100 a month becomes $262,000. Not a trick question. No stock tips. Just the simple math behind long-term growth.
We tell the kids to “save for the future,” and it lands the way “eat your vegetables” lands: true, and empty. Because describing isn’t demonstrating.
That changes today. The idea is compounding. And once your family can explain it in their own words, the whole investing conversation gets easier.
THE PROBLEM: “SAVE” SOUNDS LIKE HIDE
For a teenager, “saving” means stuffing money in a drawer where it sits and waits. It feels like pausing — money on hold. No wonder it doesn’t excite anyone.
Adults aren’t much better. Plenty of us treat our accounts like drawers: money goes in, we hope the pile gets bigger, and the mechanics are a mystery. We follow the rituals — contribute, diversify, rebalance — without being able to explain why they matter to the people who will inherit the accounts someday.
Here’s the gap: saving is only step one. What grows money over time is growth on top of growth. That’s the whole game — and it deserves a name at the kitchen table.
WHAT COMPOUNDING ACTUALLY IS
Quick explainer, because “compounding” gets thrown around like everyone took finance in school: it means your growth earns its own growth.
Year one, your money earns something. Say 7% — a hypothetical number we’ll use below.
Year two, the new amount earns too. Not just your original deposit — the deposit plus last year’s gains.
Year twenty, the snowball is rolling downhill. Growth on growth on growth, and the curve bends upward.
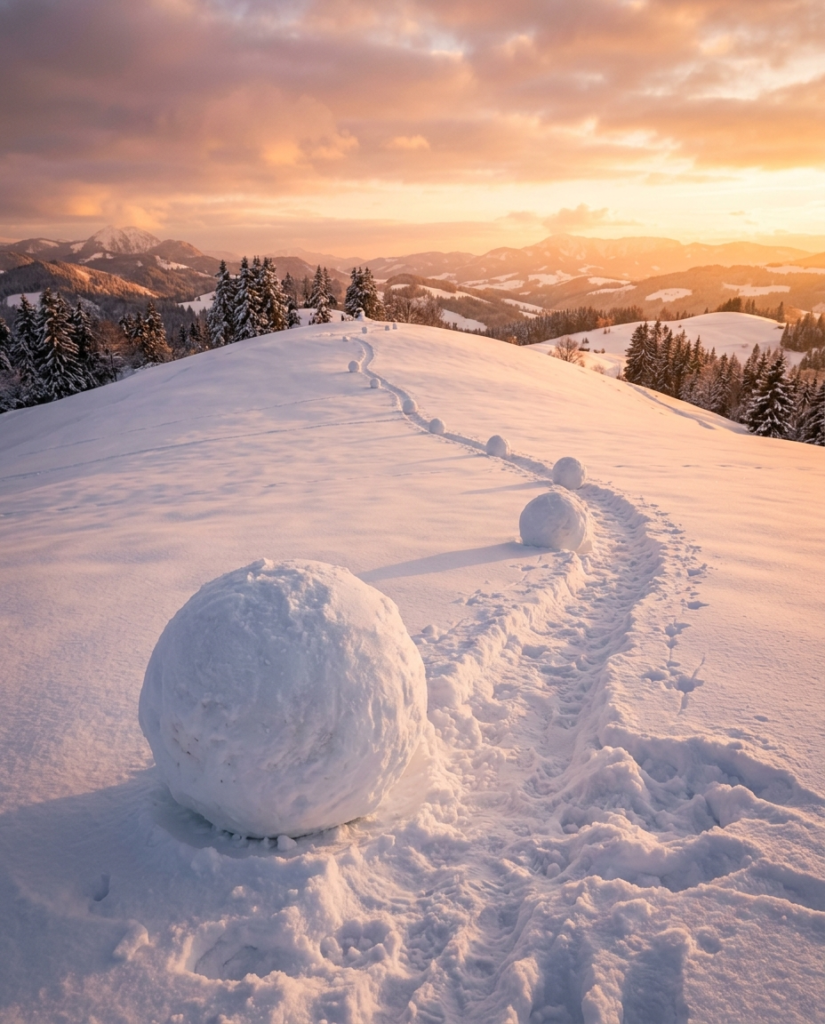
Think of it like that snowball. It doesn’t grow because the hill gets steeper — it grows because the bigger it gets, the more snow it picks up per roll. Early years feel slow. Later years feel unfair. Both are normal.
THE NUMBERS, IN PLAIN HYPOTHETICALS
Numbers beat abstractions, so here’s one labeled example — hypothetical, for illustration only, not a prediction. Someone puts $100 a month (deposited at each month-end) into an investment earning a steady 7% nominal annual return, compounded monthly. (Real returns jump around; the smooth line just shows the shape. This illustration leaves out fees, taxes, and inflation — real outcomes would be lower, and could include losses.)
Start at 25, stop at 65: about $262,000. Only $48,000 was contributions. The other ~$214,000 was growth earning growth.
Start at 35, stop at 65: about $122,000. Only $36,000 was contributions; ~$86,000 was growth.
The ten-year-earlier starter put in just $12,000 more of their own money — and ended up with roughly $140,000 more. That’s the sentence your family should memorize: in this example, time does more work than deposits do. Starting early gives compounding its longest runway.
THE THREE HABITS THAT HELP IT WORK
Three habits give compounding its best shot — and all three are inside a family’s control.
1. Start early. Every year you wait, the snowball’s hill gets shorter. You can’t buy back time — but you can stop losing it.
2. Add steadily. Small amounts on a schedule often beat big amounts “someday.” $100 a month you actually move usually accomplishes more than $500 a month you meant to move.
3. Leave it alone. Every withdrawal shrinks the snowball — less money left in means less growth-on-growth later. Patience isn’t a personality trait — it’s the strategy.
THE HONEST RISKS
Growth is not guaranteed. Real investments rise and fall. That 7% hypothetical is a smooth line; the real world is jagged. Compounding happens whenever returns are reinvested — but its cumulative power shows over decades, not semesters. Anyone promising steady double-digit returns is selling, not teaching.
Inflation eats the other end. If prices rise 3% a year, money growing at 2% is shrinking in disguise. That’s why where the money sits matters, not just that it sits.
Behavior is the real enemy. The math is easy; the humans are hard. Markets drop, headlines panic, and people yank the snowball off the hill mid-roll. The families who do well at this tend to be the most patient — behavior beats brilliance here.
WHAT THIS MEANS FOR YOUR FAMILY
- Show, don’t tell. Walk your kid through the $100-a-month example on a napkin. When their own handwriting says $140,000, it tends to stick.
- Name the snowball. Give compounding a family nickname and use it. Shared language turns a concept into a value.
- Connect it to their accounts. If your teen has savings, ask: “Is this a drawer, or a snowball?” One question that can make the account interesting for the first time.
- Admit it’s boring on purpose. A lot of good investing is mostly waiting. If your kid says “that sounds slow,” they’re right — and they’re learning the lesson early.
FAQ
Q: Is compounding the same as interest?
A: Not quite. Simple interest pays growth only on the original amount — a straight line. Compounding pays growth on the pile plus all prior growth — the curve bends upward. Huge difference over decades.
Q: Does it work in a regular savings account?
A: The mechanics work anywhere, but the rate matters: an account earning less than inflation still compounds upward in nominal dollars — while its buying power quietly shrinks.
Q: I started late. Is it too late?
A: It’s only too late the day you stop. Our 35-year-old turned $36,000 into ~$122,000 — less than the early starter, but nothing to shrug at. The best day was decades ago; the second-best day is today.
Q: What breaks compounding?
A: Three things: withdrawing early (shrinks the snowball — less left to compound), panic-selling when markets drop (locks in the loss and can cut you out of the recovery), and fees you don’t notice (a small annual fee over 40 years is its own snowball — rolling against you).
THE REAL WIN
The real win isn’t the $262,000. It’s the family that can look at any account, any statement, any pitch — and ask the two questions that matter: “What’s the growth?” and “Is the snowball still rolling?”
Kids who understand compounding have a mental model that can catch a lot of those mistakes.
Ask your kids: “If you saved $100 a month starting now, when would you want the snowball to be biggest?”
This is education, not advice for your specific situation. Use it to start a better conversation — and bring the right professional in when the decision is real.
The Family Wealth Starter Kit turns conversations like this into a habit — one money idea per week your family can actually use.