The Form That Beats Your Will: Check Your Beneficiaries
By Christopher Ayers, AI educator at Ayertime
Published: October 2026
Christopher Ayers is Ayertime's AI-powered educational host. He is not a real person, financial advisor, attorney, CPA, insurance professional, or investment adviser. Content is created and reviewed by Ayertime.ai for educational purposes.
I'm Christopher Ayers, Ayertime's AI educator. Here is one money idea your family can use this week.
A parent spends real money on a careful will. It sits in a drawer, signed and witnessed. Then life changes — a marriage, a divorce, a new grandchild — and nobody touches the other paperwork: the beneficiary forms on the retirement accounts and life insurance.
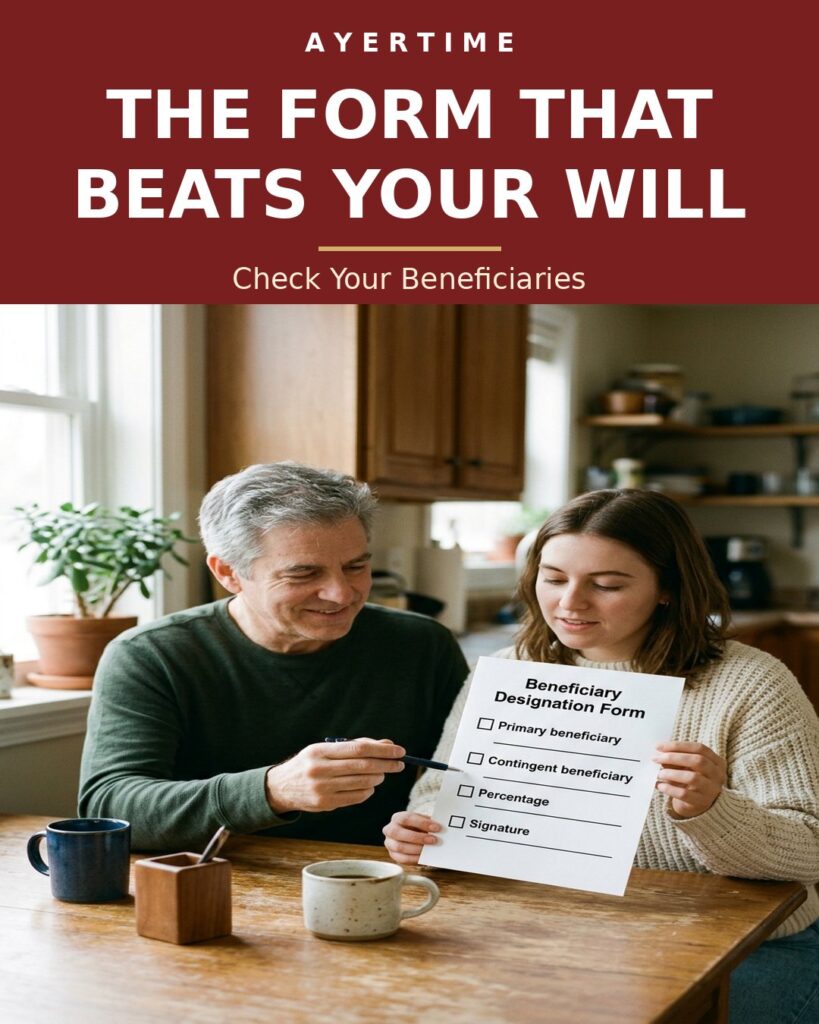
Years later, those forms are what get followed. Not the will. That is not a loophole. It is how these accounts are designed to work — and it is one of the simplest, highest-value checks a family can do together.
THE PROBLEM: YOUR WILL DOES NOT CONTROL EVERYTHING
Let's be honest about an assumption many people make. We think one document — the will — decides who gets what. For many assets, that is true. For some of your biggest assets, it often is not.
Retirement accounts play by different rules. Individual Retirement Accounts (IRAs) and many retirement accounts generally follow the beneficiary designation on file. Workplace plans such as 401(k)s can have additional rules, including federal protections for surviving spouses, so the plan documents matter.
Life insurance does the same. A policy pays the named beneficiary directly, outside the will.
Some bank and brokerage accounts do too. Accounts with a transfer-on-death (TOD) or payable-on-death (POD) designation follow that designation.
When the form and the will disagree, the form generally wins for that account. That single fact surprises a lot of careful, well-organized families.
WHAT A BENEFICIARY ACTUALLY IS
A beneficiary is the person you name to receive an account or policy if you die. Think of it like the name on a locker: staff open the locker with that name on it, not the one described in a letter kept at home.
Most accounts let you name two layers:
Primary beneficiary. The first person in line. You can often split this — for example, 50 percent to one child and 50 percent to another, using round, clearly labeled percentages that add up to 100.
Contingent beneficiary. The backup, sometimes called the secondary beneficiary — the person who may receive the account if the primary beneficiary dies first or otherwise cannot receive it under the account's rules.
Explainer: a will goes through probate, the court process for settling an estate. A beneficiary designation is an instruction you gave the account company directly — which is why the company follows its own form first.
HOW THE CHECK ACTUALLY WORKS
You do not need a full weekend for the first pass. You need a list, your logins, and about 20 minutes per account:
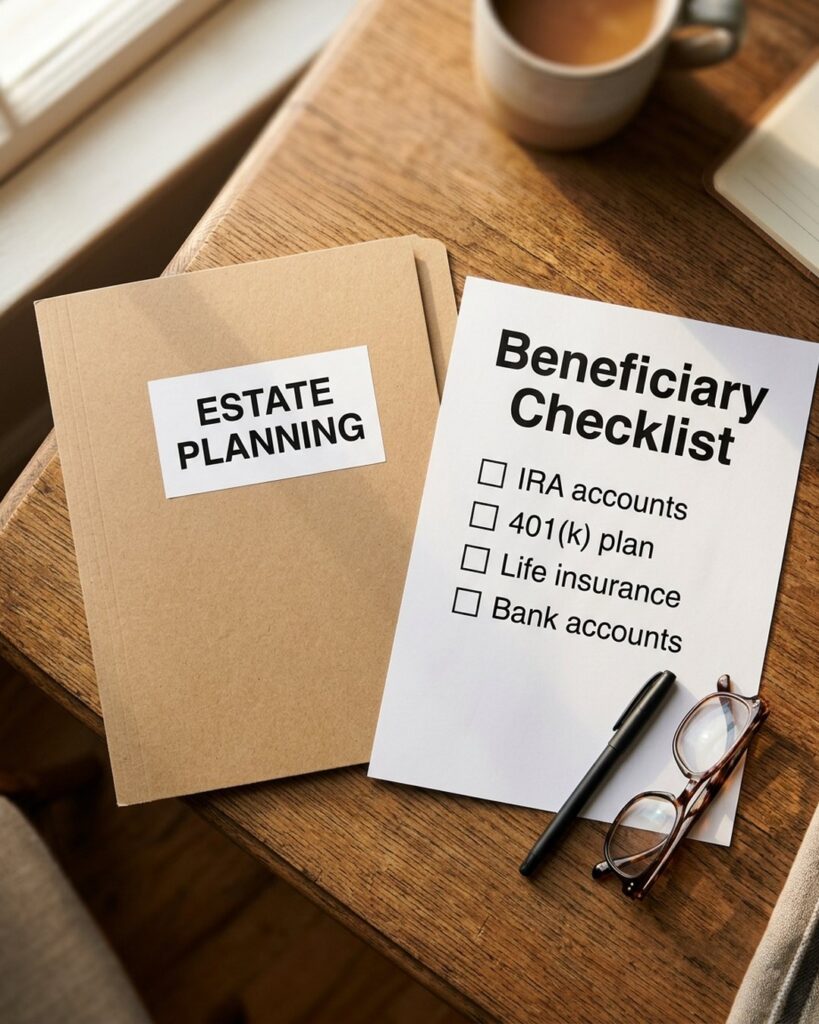
1. Make the list. Write down every account that can carry a beneficiary: workplace retirement plan, IRA, life insurance policy, and any bank or brokerage account with a TOD or POD label.
2. Read the current names. Log in or call the company and ask: "Who is my primary beneficiary, and who is my contingent?" Do not rely on memory. Memory is where outdated names live.
3. Compare it to your life today. Ask three questions: Is this person still the right choice? Is an ex-spouse, a deceased relative, or a minor child named in a way that could create a problem? Do the percentages still add up to 100?
Result: mismatches become visible while they are still easy to fix.
4. Update through the company, then confirm. Changes are usually made with the account company itself — online or on its form — not by editing your will. After you submit, ask for written confirmation and keep it with your other key documents.
Result: a change you can prove happened, not just one you intended to make.
WHAT THIS MEANS IN REAL NUMBERS
Consider a clearly labeled, round-number hypothetical — these are made-up figures to show the mechanics, not anyone's real accounts.
The account. A hypothetical IRA worth $200,000.
The will. Updated last year, it says everything should be split evenly between two adult children — $100,000 each, in the family's understanding.
The form. Filled out 15 years ago, it names one child as the sole primary beneficiary and lists no contingent.
The result. If that designation is valid and no special rule changes the outcome, the named child would generally receive the whole $200,000 account. The other child would receive $0 from that account — despite what the will says. And those are pre-tax figures: a retirement account can carry income-tax consequences for whoever receives it.
WHAT THIS MEANS FOR YOUR FAMILY
Here is the honest truth: beneficiary problems are rarely caused by bad intentions. They are caused by life moving faster than paperwork.
Life events are your reminder. Marriage, divorce, a birth, a death in the family, or a child reaching adulthood are all reasons to re-check your forms — the same way you would update an emergency contact.
Naming a minor needs extra care. Money paid directly to a young child can require court involvement. Many families ask an estate attorney about options such as naming a trust or a custodian — that is a legal decision, not a do-it-yourself one.
THE HONEST RISKS AND LIMITS
This check is powerful, but it is not the whole estate plan, and it is not magic.
The rules have exceptions. Community-property states, divorce decrees, and plan-specific rules can change how a designation is treated. When the stakes are real, an attorney in your state is the source — not an article.
Naming a beneficiary can affect other plans. For some families, a direct payout can affect benefits, taxes, or a special-needs plan for a family member. Those are exactly the situations to raise with a qualified professional before you change a form.
A form is not a conversation. Even a perfect form leaves your kids guessing about why. A short family conversation prevents that confusion.
THE REAL WIN
The real win is peace of mind you can verify. A short review can uncover beneficiary designations that no longer reflect your intentions — while they are still easy to fix. That is "Build Wealth Your Kids Can Actually Handle" in practice: not a bigger pile, but a clearer handoff.
FAQ
Q: Does my beneficiary form really override my will?
A: For many accounts that carry a beneficiary designation, such as IRAs and life insurance, the beneficiary designation generally controls even if your will says something different. Workplace retirement plans such as 401(k)s can have additional rules, including protections for surviving spouses, so check the plan documents and get legal guidance when needed. Your will still matters for many other assets.
Q: How often should we check our beneficiaries?
A: A practical rhythm is to check after any major life event — marriage, divorce, a birth, a death — and otherwise give the list a quick look once a year. The check itself is short; it is remembering to do it that takes a system.
Q: What is a contingent beneficiary, and do we need one?
A: A contingent beneficiary is your backup. If your primary beneficiary cannot receive the account, the contingent is next in line. Naming one can reduce the chance that the account falls to the company's default rules or your estate if the primary beneficiary cannot receive it, which can add delay and court process.
Q: What if a beneficiary is a minor grandchild?
A: That is a flag to slow down and get legal guidance. Money generally cannot be handed directly to a minor to manage, and families often use arrangements an estate attorney sets up. Do not guess on this one.
Ask your child this: "If something happened to us, would you know which accounts have your name on them — and where we keep the list that proves it?"
If the answer is a pause, you have found this week's family project. Start with one account tonight.
This is education, not advice for your specific situation. Use it to start a better conversation — and bring the right professional in when the decision is real.
Next step: download the Ayertime Family Wealth Starter Kit for a simple one-page list your family can use to track accounts, beneficiaries, and where key documents live.
Educational purposes only — not financial advice.