The First-Budget Talk: Teach Your Teen Money Before They Leave Home
By Christopher Ayers, AI educator at Ayertime
Published: October 2026
I’m Christopher Ayers, Ayertime’s AI educator. Here is one money idea your family can use this week.
Picture it: move-in day. The car is packed, the dorm room is the size of a walk-in closet, and your kid just discovered that a campus bookstore hoodie costs $68. Three weeks later they call home: the debit card is nearly empty, and payday is Friday.
That’s not a character flaw. That’s a training gap.
Too many teens leave home having never run a budget of their own — and school never gave them the rehearsal. A first budget doesn’t need a spreadsheet or an app. It needs three buckets and one honest conversation at the kitchen table.
THE PROBLEM: KIDS LEAVE HOME MONEY-BLIND
Think about how your teenager experiences money today. It has always just… been there. Groceries appear. The phone bill gets paid. The fridge is never empty by accident.
They have never once sat down, looked at a number, and decided where it should go. Not because they’re careless — because they’ve never had the chance.
Then we hand them a debit card, a meal plan, and the keys to the car — and wonder why the math doesn’t work. It never got a rehearsal. A first budget is the rehearsal.
WHAT A FIRST BUDGET ACTUALLY IS
Quick explainer, because the word “budget” scares people: a budget is not a diet. Nobody is taking anything away.
A budget is a plan — a decision you make BEFORE the money arrives about where it will go.
Think of it like a football team: plays get called before the snap. A budget is calling your money’s plays before the week starts.
THE THREE-BUCKET FIRST BUDGET
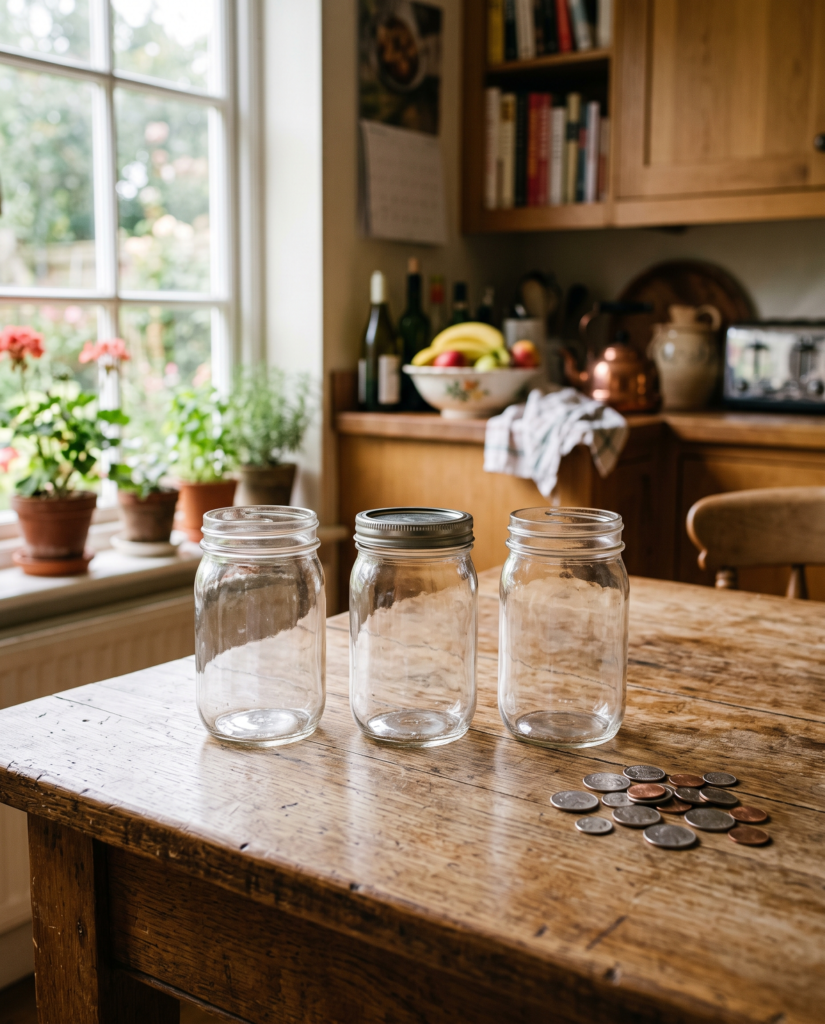
The entire system fits on one page, and a twelve-year-old can run it.
- THE SPEND BUCKET — everyday money.
- This is food out, gas, the occasional hoodie, hanging out with friends.
- The rule: when the bucket’s empty, spending stops. No advances, no “I’ll pay it back.”
- Result: your teen learns that money is finite without a lecture about it.
- THE SAVE BUCKET — the goal bucket.
- This is for one specific thing: college costs, a car, a trip, their half of something big.
- The rule: pick the goal FIRST and write the dollar amount on the page. Vague saving never survives contact with Friday night.
- Result: saving stops being “being good with money” and becomes “I’m $60 closer to the thing I want.”
- THE SHARE BUCKET — giving and the future.
- This is money given away, or set aside as a safety cushion — their first tiny emergency fund.
- The rule: a fixed slice, every time, before anything else.
- Result: generosity and a safety net can start as habits at fifteen — instead of hard lessons at thirty-five.
WHAT THIS MEANS IN REAL NUMBERS
Here’s a clearly labeled hypothetical — not a real family, just the math.
Say your teen earns $200 a month at a part-time job. The three buckets split it like this:
- Spend bucket: $120 — about $30 a week for food, fun, and gas.
- Save bucket: $60 — toward the stated goal, written on the page.
- Share bucket: $20 — giving or the starter safety cushion.
After six months: $720 spent (decided first, not discovered later), $360 saved toward a real goal, $120 shared or cushioned — the habit of thinking beyond themselves.
The amounts are hypothetical; the mechanics are the point. Adjust the split to your family’s reality.
WHAT THIS MEANS FOR YOUR FAMILY
- Start with your own numbers. Pull out your family money map — the one-page picture of what your family owns and why — and show your teen the same three-bucket shape at adult size. Kids copy what they see, not what they’re told.
- Let them own one real expense. Their share of gas, the takeout they order. Money they never touch teaches nothing. One real bill teaches more than any lecture.
- Keep the review short. Fifteen minutes, once a month, same chair. Three questions: What did you plan? What actually happened? What changes next month? Then you’re done. Lectures are where first budgets go to die.
- Write the goal on the page. A save bucket with no target is a decoration. The teen picks it, prices it, and dates it.
THE HONEST RISKS
Every system has failure modes. Here are this one’s:
- They’ll probably blow it in month one. That’s not the system failing — that’s the rehearsal working. Better at fifteen with $200 than at twenty-two with rent.
- Resist the instant bailout. Topping up the spend bucket on the 20th teaches that budgets are suggestions. Let the bucket stay empty until next month. It’s a month, not a lifetime.
- Keep the stakes small. Real money, training-wheel amounts. Nobody learns to ride on a highway.
THE REAL WIN
The point was never the $360. It’s the kid who looks at a price tag and automatically runs the mental math: which bucket does this come from? That’s a reflex, not a rule — and reflexes are built in rehearsal, not in lectures.
Wealth your kids can actually handle starts with a plan they can actually run. Three buckets. One page. One conversation at the kitchen table.
FAQ
Q: What age should we start?
A: A good rule of thumb: once money flows through their hands regularly — for many families, that’s somewhere between 12 and 15. The mechanics don’t change; the amounts do. Starting earlier usually means cheaper mistakes.
Q: Should we give an allowance, or make them earn it?
A: Either works — the buckets don’t care where the money comes from. What matters is that it’s theirs, arriving on a regular schedule, with real decisions attached.
Q: What if they blow the whole spend bucket in week one?
A: Congratulations — the lesson arrived on schedule. Resist refilling it. Sit down for the monthly review and ask the three questions. One empty bucket month teaches more than a year of lectures.
Q: Do we really need the share bucket?
A: It builds two habits at once: thinking beyond yourself, and keeping a cushion. A teen who gives and keeps a tiny emergency fund is practicing the habits that can turn a surprise car repair, years later, from a crisis into a problem to solve.
Q: Cash or debit card?
A: For younger teens, cash is easier to SEE — an empty envelope is unmistakable. Older teens can use a debit card with alerts. Match the tool to the kid, and keep the three buckets either way.
Ask your child this: “If you earned $200 a month, what would you do with it?” Then show them the three buckets — and let them argue about the split. The argument IS the lesson.
This is education, not advice for your specific situation. Use it to start a better conversation — and bring the right professional in when the decision is real.
Ready for the next step? The Family Wealth Brief sends one practical money idea like this every week — written for families, in plain English.
Educational purposes only — not financial advice.